Square has become one of the defining financial technology companies of the past decade by turning a smartphone and a small card reader into a full point-of-sale system, then expanding that foundation into banking, software, payroll, lending, and consumer payments. In practical terms, Square is both a commerce platform and a financial services provider: it helps sellers accept payments, manage operations, and access capital, while its broader ecosystem connects businesses with customers who increasingly expect fast, seamless digital transactions. That combination matters because small and mid-sized businesses have historically been underserved by traditional merchant acquirers and banks, facing opaque fees, rigid contracts, and fragmented software. Having worked with merchants that moved from legacy terminals to Square, I have seen the change firsthand: setup times dropped from weeks to hours, reporting became usable, and owners gained visibility into sales, inventory, and staffing decisions. As a company spotlight in the Movers and Shakers space, Square deserves close attention because it did not just improve checkout. It redefined what a point-of-sale company could be by bundling hardware, software, and financial tools into one operating layer for commerce.
How Square Changed the Point-of-Sale Market
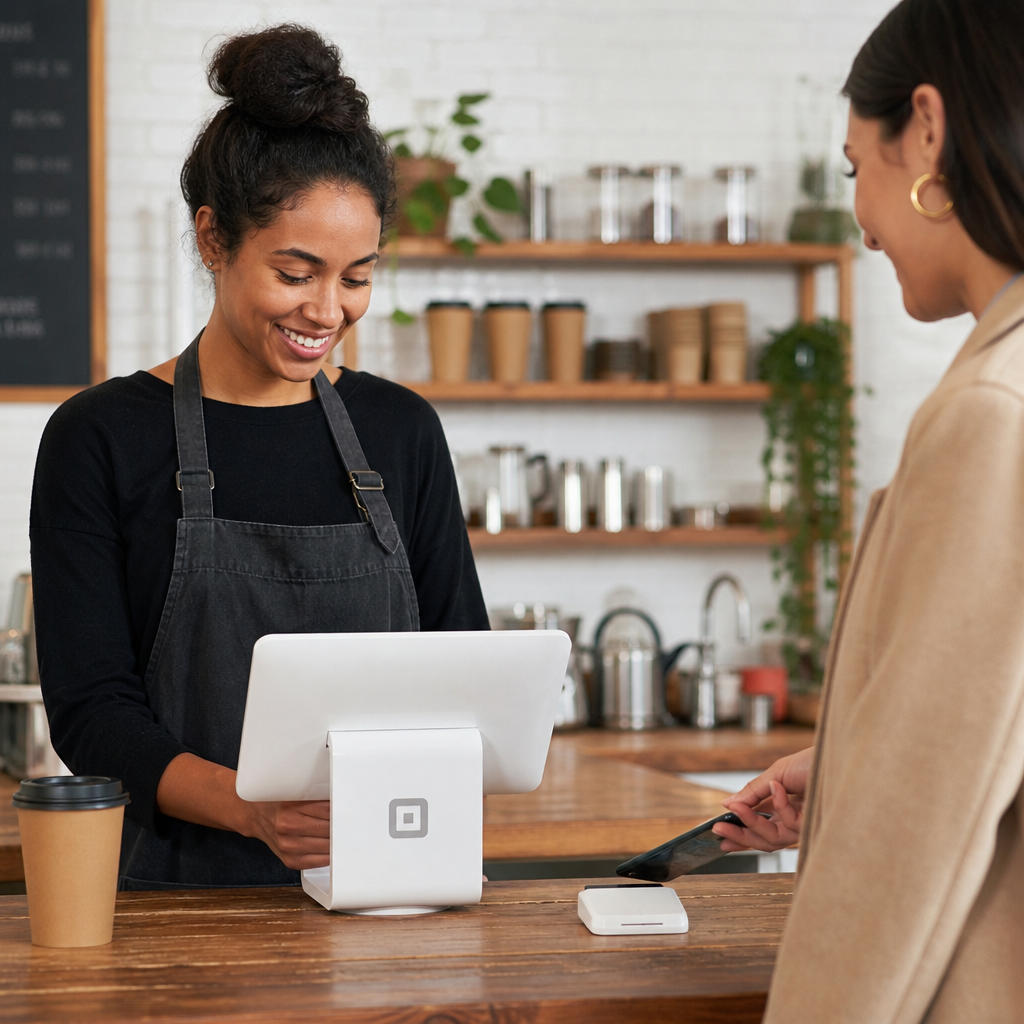
Square entered a market dominated by traditional payment processors, independent sales organizations, and bulky countertop terminals. Before Square, many small sellers, especially market vendors, food trucks, salons, and service professionals, struggled to accept card payments without expensive equipment and complex underwriting. Square’s original breakthrough was simple and commercially powerful: a small magstripe reader that plugged into a phone, paired with an app that let merchants start taking payments quickly. The product removed friction at the exact point where many businesses lost sales. Consumers already preferred cards, and later contactless wallets, but thousands of microbusinesses were still cash-heavy because card acceptance felt out of reach.
The company’s next move was even more important than the reader. Square built an integrated point-of-sale stack that combined payment acceptance, item libraries, taxes, digital receipts, tipping, and basic analytics. That integration matters because disconnected tools create operational errors. When a retailer runs one system for checkout, another for inventory, and a third for customer records, staff spend time reconciling data instead of serving customers. Square collapsed those functions into a single workflow. In restaurants, for example, Square for Restaurants added menu management, coursing, modifiers, and kitchen ticket flows. In appointments-based businesses, Square Appointments brought booking, no-show controls, and staff calendars into the payment layer. Those are not cosmetic add-ons; they directly improve throughput and reduce administrative work.
Its pricing model also changed buyer expectations. Flat-rate payment processing is not always the cheapest option for every merchant, particularly at higher volumes where interchange-plus pricing may win, but it is easy to understand. That transparency gave small businesses predictability. Just as significant, Square emphasized self-service onboarding. Merchants could sign up online, order hardware, and begin transacting without a lengthy sales cycle. That product-led growth model helped Square scale efficiently and pushed the broader POS market toward simpler packages, cleaner user interfaces, and faster deployment.
From Card Reader to Commerce Ecosystem
Square’s real strategic advantage is that it did not remain a payments tool. It evolved into a commerce ecosystem where each product reinforces the others. Sellers can use Square Register, Square Terminal, or mobile readers for in-person transactions, then layer on online checkout, invoices, gift cards, loyalty programs, marketing campaigns, and customer directories. Because these tools share a common data structure, the business owner sees one view of sales across channels. Omnichannel commerce is often presented as a buzzword, but in plain terms it means a customer can discover a business online, place an order, redeem a promotion in store, and receive a digital receipt without the merchant stitching together five separate vendors.
This ecosystem approach is especially valuable for businesses with limited administrative capacity. A coffee shop owner does not want to become a systems integrator. They need menu updates to sync across the register, online ordering page, and inventory counts. They need labor reports that show peak hours clearly enough to build next week’s schedule. They need chargeback visibility and clear settlement timing. Square addresses those needs by keeping core functions native rather than depending entirely on third-party integrations. The company still offers APIs and app marketplace connectivity, but the default experience is cohesive, which lowers training time and reduces support tickets.
Another underappreciated strength is how Square designed for category-specific use cases. Generic POS tools often fail because restaurants, retail stores, beauty professionals, and service businesses work differently. Restaurants need seat mapping and kitchen routing. Retailers need variants, stock counts, and barcode support. Salons need appointments, deposits, and staff performance tracking. By tailoring products vertically, Square improved retention and average revenue per seller. That strategy helped the company move from serving micro-merchants to winning larger, more operationally complex businesses without abandoning usability.
Financial Services Expansion and Why It Matters
Square’s move into financial services extended its value well beyond checkout. Once a platform sees transaction volume, seasonality, refund rates, and customer behavior, it can make faster and often more informed decisions about adjacent financial products. Square Capital, now part of a broader business banking offering under Block, used merchant sales data to provide financing with repayment tied to card revenue. For a seasonal business, that structure can be more practical than a fixed bank loan payment. When sales slow, repayment slows too. That does not make financing cheap or appropriate in every case, but it aligns cash flow better than many conventional products.
Square Banking added business checking, savings features, and faster access to funds. For small businesses, settlement speed is not a minor detail. If payroll, rent, or supplier invoices are due, waiting several days for card receipts to clear can create stress and borrowing needs. By tightening the connection between payment acceptance and bank-like services, Square improved working capital management. It also expanded into payroll and employee tools, giving businesses a more unified operating system. From an economic standpoint, this creates a flywheel: the more a seller uses Square, the more data Square has to improve underwriting, support, and product design.
There are tradeoffs. Relying heavily on one vendor can create concentration risk, and businesses with complex accounting requirements may still prefer specialized systems. Processing costs also deserve close review, especially for high-ticket sellers with low margins. In my experience, Square is strongest when a business values speed, simplicity, and integrated operations more than squeezing out every basis point of payment cost. For many local businesses, that is a rational choice because labor time and operational mistakes are expensive too.
Competitive Position and Industry Influence
Square operates in a fiercely competitive field that includes Shopify POS, Toast, Clover, Lightspeed, PayPal Zettle, Stripe for certain commerce flows, and traditional merchant services providers. What distinguishes Square is the breadth of its seller tools combined with approachable onboarding. Toast may be stronger for some full-service restaurant environments, and Shopify is deeply compelling for retail brands with digital-first DNA, but Square remains unusually versatile across merchant sizes and categories. That versatility has made it a benchmark company in fintech and commerce infrastructure.
Its influence extends beyond direct market share. Square normalized mobile card acceptance, accelerated contactless and wallet-ready hardware adoption, and pushed software-led merchant acquiring into the mainstream. Competitors now emphasize sleek hardware, cloud dashboards, and integrated business services because Square proved merchants would reward ease of use. The company also benefited from larger shifts in consumer behavior, including card preference, QR code familiarity in some sectors, online ordering growth, and demand for digital receipts. During the pandemic period, businesses that already had integrated online and in-person tools adapted faster, and Square’s product mix positioned it well to support curbside pickup, invoices, and remote payments.
| Area | Square Strength | Key Limitation | Best Fit Example |
|---|---|---|---|
| In-person POS | Fast setup, intuitive hardware, unified software | May lack deep enterprise customization | Independent retailer with one to five locations |
| Restaurants | Accessible restaurant workflows and online ordering | Some complex full-service operations need more depth | Quick-service cafe or counter-service concept |
| Financial tools | Integrated banking, payments, payroll, and financing | Single-vendor dependence can increase platform risk | Small business prioritizing cash-flow visibility |
| Commerce growth | Omnichannel selling and customer engagement tools | Advanced customization may require third-party apps | Local brand expanding from store to online sales |
Leadership, Brand Evolution, and the Block Connection
Square’s story is also a leadership and brand story. Co-founded by Jack Dorsey and Jim McKelvey, the company emerged from a straightforward merchant pain point: difficulty accepting card payments for small, everyday transactions. That origin mattered because the product was built around a real seller problem rather than a top-down banking theory. Over time, Square became part of a broader corporate identity under Block, reflecting an expanded ambition that included seller services, Cash App, music streaming through TIDAL, and blockchain-related initiatives. Even with that broader structure, the Square brand remains strongly associated with merchant commerce and point-of-sale innovation.
Brand trust is central in payments. Merchants need confidence that hardware will work during peak hours, funds will settle correctly, disputes will be handled transparently, and software updates will not disrupt operations. Square built that trust through consistent design, clear onboarding, and a recognizable physical presence at counters, farmers markets, and service businesses. The brand also benefited from making payments feel less intimidating. Owners who once avoided card acceptance began to see it as manageable. That psychological shift should not be underestimated; financial inclusion in commerce often starts with product clarity.
For readers exploring Company Spotlights and the broader Movers and Shakers landscape, Square stands out because it changed both technology expectations and business behavior. It showed that merchant services could be software-first, design-led, and accessible without losing seriousness. It also demonstrated how a payments company can extend logically into adjacent financial services when it has strong transaction data and trusted merchant relationships. If you are mapping the companies shaping modern commerce, study Square closely, compare its model with peers across POS, merchant acquiring, and business banking, and use those lessons to understand where financial services innovation is heading next.
Frequently Asked Questions
What is Square, and why has it become such an important player in point-of-sale and financial services?
Square is a financial technology company that began by solving a very practical problem for small businesses: how to accept card payments easily and affordably without investing in expensive traditional point-of-sale hardware. Its original breakthrough was simple but powerful—a compact card reader that connected to a smartphone or tablet, turning that device into a payment terminal. That innovation lowered the barrier to entry for merchants, freelancers, market vendors, and small retailers that had often been underserved by legacy payment providers.
What makes Square especially important today is that it evolved far beyond payment acceptance. It now operates as a broader commerce and financial services ecosystem. In addition to processing in-person and online transactions, Square provides tools for inventory tracking, employee management, payroll, invoicing, appointment booking, customer engagement, reporting, business banking services, and access to financing. This means businesses can run much of their day-to-day operation through a single integrated platform rather than patching together multiple systems from different vendors.
Square’s importance also comes from the way it bridges commerce and finance. It does not just help sellers collect money; it helps them manage cash flow, analyze business performance, borrow capital, and connect with customers. On the consumer side, its broader ecosystem has extended into digital payments and financial tools, creating a network effect between buyers and sellers. That combination of accessibility, integration, and financial utility is a major reason Square has become one of the defining fintech companies of its era.
How did Square change the traditional point-of-sale model for small businesses?
Square changed the traditional point-of-sale model by making it dramatically easier, faster, and more cost-effective for businesses to start accepting electronic payments. Before Square’s rise, many small merchants faced a complicated process when setting up card acceptance. They often needed merchant accounts, long-term contracts, dedicated terminals, upfront equipment purchases, and pricing structures that were difficult to understand. For very small businesses or new entrepreneurs, that friction could be enough to keep them cash-only.
Square simplified this model by offering an accessible setup with transparent pricing and mobile-friendly hardware. A business owner could sign up, receive a card reader, and begin taking payments with minimal technical expertise. That ease of adoption opened the door for a wide range of sellers, including food trucks, pop-up shops, independent service providers, artists, and local retailers. In effect, Square helped modernize commerce for a segment of the market that had often been overlooked by traditional payment providers.
Just as important, Square redefined what a point-of-sale system could be. Instead of functioning only as a card terminal, the POS became the central operating system for a business. Merchants could use Square to monitor sales trends, manage catalogs, issue digital receipts, track employees, oversee inventory, and integrate in-store and online transactions. This broader functionality turned payments from a standalone activity into part of a connected business management workflow. By doing so, Square helped small businesses operate with tools that once were more common in larger enterprise environments.
What products and services does Square offer beyond payment processing?
Although Square is best known for payment acceptance, its product lineup extends well beyond card processing. At its core, the company offers a full suite of seller tools designed to support both front-end commerce and back-office operations. These include point-of-sale software for different business types, online store creation, invoicing, recurring billing, appointment scheduling, restaurant and retail management systems, and customer relationship features such as loyalty programs, marketing campaigns, and digital receipts. This broad software layer helps businesses manage how they sell as well as how they interact with customers.
Square has also expanded significantly into financial services. It offers business banking-related tools, including business accounts and debit card functionality in some markets, helping sellers access and use their funds more quickly. It provides payroll services for employers, allowing businesses to handle wages, tax filings, and employee administration within the same ecosystem they use for sales. In lending, Square uses transaction data and business performance signals to extend financing options to eligible sellers, which can help merchants secure working capital without the traditional friction associated with bank loans.
Another major part of Square’s broader value lies in integration. Because its services are connected, businesses can move from taking a payment to reconciling revenue, paying staff, funding expansion, and engaging customers without leaving the platform. This creates efficiency, reduces operational complexity, and can give merchants better visibility into the health of their business. In practical terms, Square is no longer just a checkout solution—it is a multi-layered commerce infrastructure provider with financial services built directly into the operating flow of small and medium-sized businesses.
How does Square support business growth, cash flow, and everyday operations?
Square supports business growth by giving sellers tools that address several of the most common operational challenges at once. Payment acceptance is only the starting point. Once a business begins using Square, it can gain access to sales analytics, inventory oversight, customer insights, employee tools, and digital commerce capabilities. These features help owners make more informed decisions about staffing, pricing, product mix, and marketing. Instead of relying on fragmented spreadsheets or disconnected software systems, they can work from a more centralized view of how the business is performing.
Cash flow support is another major part of Square’s appeal. Many small businesses struggle with irregular revenue timing, seasonal fluctuations, or the need to pay suppliers and employees before customer payments have fully settled. Square addresses this challenge in several ways, including faster access to funds, integrated business financial tools, and lending products for qualified sellers. Because Square processes transactions directly, it can often use real-time business data to assess sales activity and tailor financing offers. This data-driven approach can be especially valuable for businesses that may not have extensive credit histories or traditional banking relationships.
In everyday operations, Square reduces administrative burden. A restaurant can manage menu items and table service, a retailer can track stock across channels, and a service business can schedule appointments and send invoices—all within the same ecosystem. That operational simplicity matters because small business owners typically wear many hats. By combining commerce, administration, and financial management into one platform, Square helps sellers spend less time navigating systems and more time focusing on customers, growth, and profitability.
Why is Square often described as both a commerce platform and a financial services company?
Square is often described in both ways because its business sits at the intersection of transactions, software, and money management. As a commerce platform, it provides the tools businesses use to sell products and services across physical and digital channels. That includes point-of-sale hardware, checkout software, e-commerce capabilities, customer engagement tools, and operational management features. These tools enable businesses to run the commercial side of their operations more efficiently and create better buying experiences for customers.
At the same time, Square functions as a financial services company because it is involved in how money moves, how businesses access capital, and how sellers manage funds after a transaction occurs. It processes payments, facilitates deposits, supports business spending, offers payroll tools, and extends financing to eligible merchants. In other words, it does not stop at enabling a sale—it continues into the financial life cycle that follows the sale. That is a defining feature of modern fintech: embedding financial services directly into the workflows where businesses already operate.
This dual identity is one reason Square has had such a broad impact. Traditional commerce software companies may help a seller run a store, while traditional financial institutions may help with banking or lending. Square combines those functions in a more integrated and technology-driven way. The result is a platform where commerce activity generates data, that data informs financial services, and those financial services can then support further commerce growth. That feedback loop is central to Square’s strategy and explains why it is widely viewed as more than a payment processor—it is an end-to-end ecosystem for modern business and connected consumer payments.