The future of renewable energy is being shaped as much by software, semiconductors, and venture capital as by solar panels and wind turbines, and nowhere is that convergence clearer than in Silicon Valley. In practical terms, renewable energy means electricity, heat, or fuels produced from sources that replenish naturally, including sunlight, wind, water, geothermal heat, and biomass. Silicon Valley’s contribution is not simply inventing gadgets; it is building the digital systems, manufacturing methods, financing models, and startup ecosystems that make clean power cheaper, smarter, and easier to scale. I have worked with founders, energy operators, and climate software teams long enough to see a consistent pattern: the winning technologies are rarely isolated breakthroughs. They succeed when hardware, data, policy, and grid economics align.
This matters because the energy transition is no longer a niche environmental project. It is a core industrial shift affecting utilities, automakers, data centers, real estate, and national security planning. The International Energy Agency has repeatedly shown that solar photovoltaic capacity additions now outpace most other generation sources globally, while battery costs have fallen dramatically over the last decade due to manufacturing scale and chemistry improvements. At the same time, electricity demand is rising from electric vehicles, cloud computing, artificial intelligence workloads, and heat electrification. That combination creates both urgency and opportunity. Businesses need resilient energy systems. Households want lower bills and backup power. Governments need cleaner grids without sacrificing reliability. Silicon Valley sits at the center of those demands because it excels at integrating fragmented markets through technology platforms.
For readers exploring cutting-edge tech, renewable energy is an ideal hub topic because it connects multiple innovation layers. Advanced materials improve panel efficiency. Machine learning forecasts demand and weather. Power electronics convert and route electricity with less loss. Carbon accounting software verifies impact claims. Robotics reduce installation and maintenance costs. New financing tools lower the barrier for adoption. Understanding where these pieces fit helps founders spot opportunities, investors evaluate defensibility, and operators choose systems that work in the real world rather than on pitch decks. The most useful question is not whether renewables are the future. It is which technologies and business models will solve the remaining constraints fast enough to matter.
Why Silicon Valley matters in renewable energy innovation
Silicon Valley matters because it specializes in turning expensive, complex technologies into scalable products. In energy, that pattern shows up in three ways. First, startup teams apply software thinking to old infrastructure problems. Grid operators have historically relied on slow planning cycles and siloed data. New companies build forecasting engines, virtual power plant platforms, and energy management dashboards that make distributed assets behave like coordinated fleets. Second, venture-backed hardware companies shorten iteration cycles. Instead of waiting years for monolithic utility deployments, they pilot on campuses, warehouses, apartment buildings, and microgrids. Third, the region links technical talent with risk capital and enterprise customers, which speeds commercialization.
Tesla is the most visible example, not because it invented batteries, but because it integrated cells, software, thermal management, charging, and brand into a system consumers understood. Enphase did something similarly important with microinverters, improving panel-level optimization and system visibility. Sunrun and Sunnova expanded solar adoption through financing and service models rather than pure component invention. Autogrid, before its acquisition by Schneider Electric, helped demonstrate how distributed energy resources could be orchestrated as flexible grid capacity. These examples show that Silicon Valley’s edge often lies in system design and go-to-market execution, not just laboratory science.
The culture also favors cross-pollination. Engineers who once optimized cloud infrastructure now work on power market software. Semiconductor veterans bring manufacturing discipline to battery management systems. Former mobility founders launch charging, fleet electrification, or grid edge startups. That talent movement matters because modern renewable energy is an information problem as much as a generation problem. Power must be produced, stored, traded, and consumed in sync. Every improvement in sensing, prediction, optimization, and control increases the value of clean energy assets already deployed.
The technologies defining the next decade
Several technologies are defining the next decade of renewable energy, and the most important are not all generation technologies. Solar remains central because utility-scale and rooftop installations continue to deliver low-cost electricity in many markets. Advances in passivated emitter and rear contact cells, TOPCon architectures, and tandem perovskite-silicon research are pushing efficiency higher, which matters where land, rooftops, or interconnection capacity are constrained. Wind remains essential, especially offshore, though project economics depend heavily on permitting, transmission, and commodity costs. Geothermal is regaining attention as drilling and subsurface modeling improve, with enhanced geothermal systems attracting startup interest because they can provide firmer power than solar or wind.
Storage may be even more decisive. Lithium-ion remains dominant because the supply chain is mature, but it is not the final answer for every duration. Four-hour batteries help with peak shifting and ancillary services, while longer-duration technologies target overnight balancing and renewable overbuild capture. Silicon Valley investors are watching iron-air, zinc-based systems, thermal storage, and flow batteries because grid reliability depends on more than short bursts of discharge. The practical lesson is simple: choose storage by use case, not hype. A commercial building reducing demand charges has different needs than a utility replacing gas peakers.
Power electronics and software are equally critical. Inverters, battery management systems, energy management software, and advanced metering form the control layer of the clean energy stack. Without them, variable generation creates operational headaches. With them, solar arrays, EV chargers, thermostats, and batteries can respond to price signals and grid conditions in seconds. I have seen projects fail not because panels underperformed, but because controls were poorly integrated. In renewable energy, the intelligence layer often determines whether hardware becomes an asset or a headache.
| Technology | Primary value | Main limitation today | Common real-world use |
|---|---|---|---|
| Solar PV | Low-cost daytime generation | Intermittent output | Utility farms, rooftops, carports |
| Battery storage | Peak shifting and backup power | Cost at longer durations | Homes, commercial sites, grid services |
| Smart inverters | Grid-responsive power control | Interoperability complexity | Solar-plus-storage systems |
| Virtual power plants | Aggregate distributed flexibility | Customer enrollment and regulation | Utilities, demand response programs |
Software, AI, and the grid edge
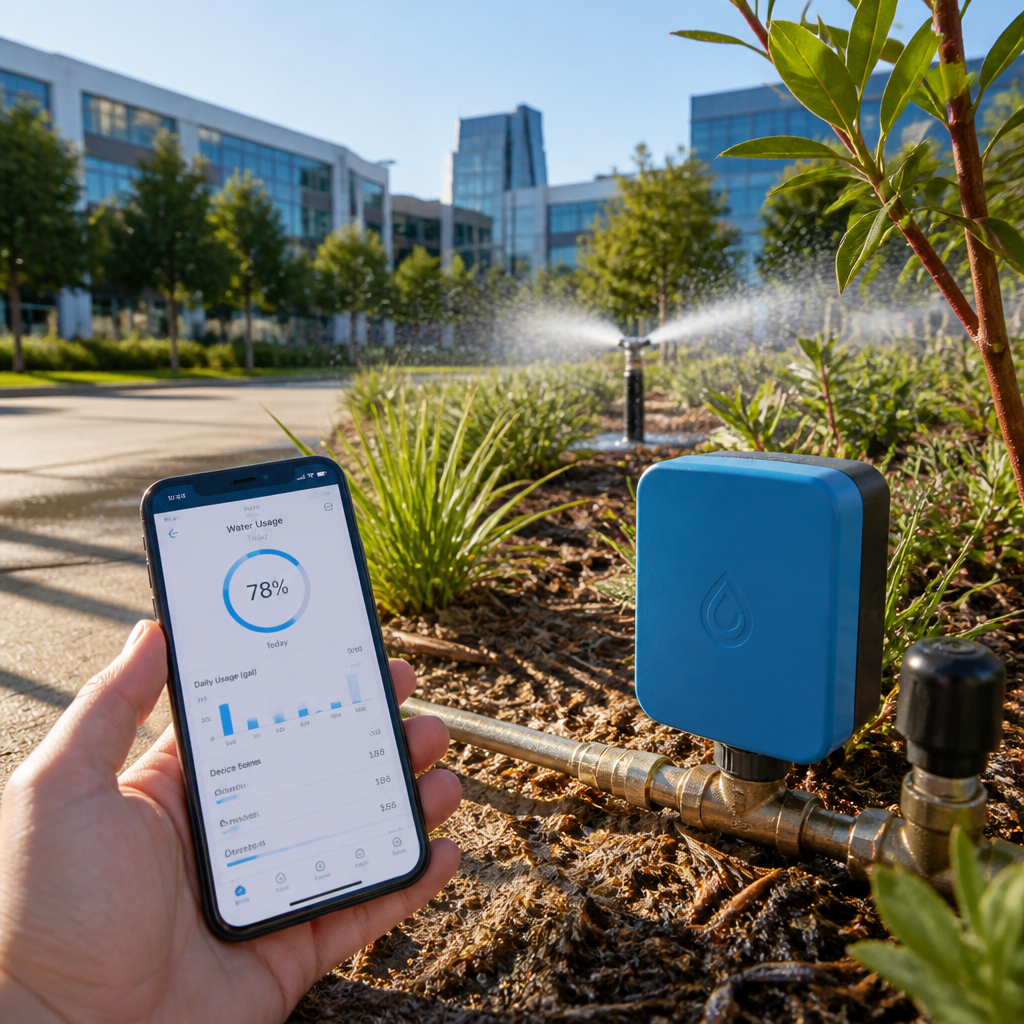
The clean energy transition increasingly depends on software, especially at the grid edge where homes, vehicles, buildings, and batteries interact with the power system. Utilities traditionally operated with one-way power flow assumptions: large plants generated electricity and consumers used it. That model is fading. Now millions of endpoints can generate, store, or shift load. Managing that complexity requires forecasting, optimization, and automation. Artificial intelligence helps predict solar production from weather patterns, detect equipment faults from telemetry, and schedule batteries around tariffs, demand response events, and wholesale market prices.
Virtual power plants are one of the clearest examples. By coordinating distributed batteries, smart thermostats, EV chargers, and flexible appliances, software can create a dispatchable resource without building a single central plant. Companies such as Tesla, Sunrun, and several utility partners have shown that aggregated residential assets can reduce peak stress and improve resilience during emergencies. California and Texas have both become proving grounds because they combine renewable penetration, grid volatility, and strong incentives for flexible demand.
Data quality is the hidden differentiator. A startup may promise AI-driven savings, but if interval meter data is incomplete, device telemetry is noisy, or utility tariff logic is outdated, optimization results deteriorate fast. The strongest platforms invest heavily in integrations, cybersecurity, and measurement and verification. Standards such as IEEE interconnection requirements and communication protocols matter because fragmented devices create operational risk. In practice, the best energy software teams behave like enterprise infrastructure companies. They obsess over uptime, latency, controls safety, and auditability, not just app design.
Capital, policy, and commercialization realities
Renewable energy does not scale on technology alone. It scales when capital and policy align with deployment realities. Silicon Valley brings abundant early-stage funding, but energy startups face longer timelines and heavier infrastructure dependencies than typical software companies. Interconnection queues, permitting, supply contracts, and regulatory approvals can delay revenue even when the core product works. That is why the strongest founders understand project finance almost as well as engineering. They know how tax credits, power purchase agreements, leasing structures, and utility incentives shape adoption.
In the United States, federal incentives have changed the commercialization map by improving the economics of domestic manufacturing, storage deployment, and clean power procurement. State-level rules further influence outcomes through net metering, community solar frameworks, and resource adequacy programs. For startups, policy literacy is not optional. A battery company selling into California faces a different opportunity set than one targeting industrial resilience in the Southeast or microgrids for islanded communities. Good strategy starts with market design.
Commercialization also depends on trust. Energy buyers are cautious because system failures affect operations, safety, and brand reputation. Enterprise customers ask hard questions about warranties, degradation curves, installer quality, software support, and bankability. That skepticism is healthy. I have seen buyers choose a slightly less ambitious solution from a proven integrator because financing, maintenance, and performance guarantees were clearer. In energy, credibility lowers customer acquisition cost.
What to watch next across startups and industry
Over the next several years, watch for convergence across sectors rather than isolated category winners. Electric vehicles will increasingly act as flexible loads and, in some cases, storage assets. Data centers will sign more clean power deals while investing in onsite generation, microgrids, and advanced cooling. Building electrification platforms will combine heat pumps, panels, batteries, and controls into one upgrade path. Industrial companies will adopt energy management software not only to cut emissions but to hedge price volatility and improve resilience. These are not speculative trends. They are already visible in procurement strategies across technology campuses, logistics fleets, and commercial real estate portfolios.
The biggest insight from Silicon Valley is that renewable energy becomes transformative when it is treated as a full-stack problem. Generation matters, but integration matters more. The durable companies will connect hardware, software, financing, and operations into products customers can trust. For anyone following tech innovations and startups, this hub topic offers a clear lens on where deep technology meets urgent market demand. Explore the adjacent themes in storage, grid software, electrification, and climate finance, then evaluate each new idea by one standard: does it make clean energy cheaper, more reliable, or easier to deploy at scale?
Frequently Asked Questions
How is Silicon Valley influencing the future of renewable energy beyond just building solar panels and wind turbines?
Silicon Valley is shaping renewable energy by applying its strengths in software, semiconductors, data analytics, automation, and venture-backed innovation to the energy sector. While traditional renewable energy development often focuses on physical infrastructure such as solar farms, wind projects, and battery installations, Silicon Valley’s role is increasingly centered on the digital and operational intelligence that makes those assets more efficient, scalable, and economically competitive. This includes artificial intelligence for energy forecasting, cloud platforms for grid management, advanced sensors for performance monitoring, and power electronics that improve how electricity is converted, stored, and distributed.
One of the most important contributions is the creation of smarter energy systems. Renewable energy sources like solar and wind are variable by nature, so balancing supply and demand requires sophisticated control systems. Silicon Valley companies and research networks are helping utilities and energy developers predict generation patterns, optimize battery dispatch, detect equipment failures early, and integrate distributed energy resources such as rooftop solar, electric vehicles, and home batteries. In that sense, the region is not replacing the physical side of renewable energy; it is making the entire clean energy ecosystem more responsive, efficient, and resilient.
Silicon Valley also plays a major role in financing and scaling emerging technologies. Venture capital helps move promising clean energy ideas from laboratory concepts to commercial products faster than would often be possible through traditional utility development cycles alone. Whether the focus is grid software, long-duration energy storage, next-generation semiconductors, or electrification platforms, the Valley’s startup culture encourages rapid iteration and commercialization. The result is that renewable energy innovation is increasingly driven by the same forces that transformed computing and communications: speed, data, integration, and platform thinking.
Why are software and artificial intelligence becoming so important in renewable energy systems?
Software and artificial intelligence are becoming essential because modern renewable energy systems are far more complex than simply producing electricity from sunlight or wind. Renewable generation is decentralized, variable, and increasingly connected to millions of devices across homes, businesses, vehicles, batteries, and utility networks. Managing all of these moving parts in real time requires digital tools that can analyze huge volumes of data and make precise operational decisions much faster than human operators could on their own.
For example, AI can improve weather forecasting to predict how much electricity a solar or wind installation will generate over the next few minutes, hours, or days. That is critically important for grid operators, who need to match supply with demand continuously. Machine learning systems can also identify performance losses in solar arrays, detect maintenance issues in wind turbines before they cause outages, and optimize battery charging and discharging to lower costs while protecting equipment life. In commercial and residential settings, software can automatically shift energy use to times when renewable power is abundant and cheaper, reducing strain on the grid.
Just as importantly, software helps coordinate distributed energy resources. As more people install rooftop solar, electric vehicle chargers, smart thermostats, and home energy storage, the grid becomes less centralized and more dynamic. Platforms developed with Silicon Valley-style engineering can aggregate these resources into virtual power plants, allowing many small assets to act like a single large power resource. This improves reliability, supports renewable integration, and creates new economic opportunities for consumers. In practical terms, software and AI are becoming the operating system of the clean energy transition, turning renewable energy from a collection of hardware assets into a highly optimized, intelligent network.
What role do semiconductors and advanced manufacturing play in the renewable energy transition?
Semiconductors are foundational to renewable energy because they control how electricity is generated, converted, stored, and used. In solar systems, semiconductor materials are at the heart of photovoltaic cells that convert sunlight into electricity. In batteries, electric vehicles, inverters, smart meters, and grid equipment, advanced chips and power electronics manage energy flows with precision. Silicon Valley’s long-standing expertise in chip design, fabrication technologies, and electronics innovation gives it a significant influence over how efficiently renewable energy systems perform and how quickly they can improve over time.
Power semiconductors are especially important. Devices made from materials such as silicon carbide and gallium nitride can handle higher voltages, operate at higher temperatures, and switch electricity more efficiently than older technologies. That means lower energy losses in solar inverters, faster charging for electric vehicles, more compact grid equipment, and better overall system performance. These gains may seem incremental at the component level, but across large energy networks they translate into substantial efficiency improvements, lower costs, and better reliability.
Advanced manufacturing matters just as much as the underlying technology. Renewable energy growth depends not only on invention but also on the ability to produce hardware at scale with consistent quality and reasonable cost. Silicon Valley’s influence extends into manufacturing automation, robotics, quality control software, and supply chain optimization. These capabilities can accelerate the commercialization of new battery chemistries, next-generation solar materials, and grid hardware. In short, semiconductors and advanced manufacturing form the technical backbone of the energy transition, enabling renewable systems to become smarter, cheaper, and more scalable.
How does venture capital affect the development of renewable energy technologies?
Venture capital affects renewable energy by providing the risk-tolerant funding needed to develop and test new technologies before they are ready for large-scale deployment. Clean energy innovation often requires significant upfront investment, long development timelines, and technical validation under real-world conditions. Traditional lenders and infrastructure investors usually prefer proven technologies with predictable returns, so venture capital helps bridge the gap between early invention and commercial maturity. In Silicon Valley, that funding model has helped launch companies working on grid software, battery systems, carbon-aware energy management, electrification services, and other technologies that support renewable energy adoption.
Beyond money, venture capital can also speed execution. Investors often bring strategic guidance, industry networks, recruiting support, and access to potential partners or customers. Startups backed by experienced firms may be able to refine their products faster, pilot them with utilities or large enterprises, and scale more aggressively once the business model is validated. This is particularly important in renewable energy, where timing matters. Technologies that reduce grid congestion, improve storage economics, or enable better integration of clean power can have outsized impact if they reach the market quickly.
That said, venture capital also shapes the kinds of energy solutions that get attention. Investors often favor scalable, software-driven, or modular businesses that can grow quickly, which can be an advantage for digital energy platforms and distributed energy technologies. However, some critical clean energy sectors, especially capital-intensive infrastructure or hardware-heavy innovations, may require more patient financing models. The most effective renewable energy ecosystem usually combines venture capital, corporate partnerships, public policy support, project finance, and industrial investment. Silicon Valley’s contribution is strongest when its appetite for innovation is paired with the long-term realities of energy deployment.
What are the biggest challenges Silicon Valley and the renewable energy sector still need to solve?
Despite major progress, several challenges remain before renewable energy can fully meet future demand in a reliable, affordable, and equitable way. One of the biggest issues is grid integration. Solar and wind generation are growing rapidly, but many power grids were originally designed for centralized fossil fuel plants, not for variable renewable resources and millions of distributed devices. Upgrading transmission systems, modernizing local distribution networks, and improving grid software are all essential. Silicon Valley can contribute advanced digital tools, but technical solutions still need to work within real-world utility structures, regulatory rules, and infrastructure constraints.
Energy storage is another major challenge. Batteries have improved dramatically, especially for short-duration use, but the energy system also needs cost-effective long-duration storage to cover periods when renewable generation drops for extended stretches. In addition, supply chains for batteries, solar components, and key minerals must become more secure, diversified, and sustainable. Manufacturing scale, recycling systems, and responsible sourcing will all influence how quickly renewable technologies can expand without creating new dependencies or environmental pressures.
There is also the challenge of affordability and access. Clean energy innovation is most valuable when it benefits not only utilities, corporations, and affluent homeowners, but also renters, lower-income communities, and regions with aging infrastructure. Technologies developed in innovation hubs must be deployable in practical, cost-sensitive environments. Finally, the sector must align fast-moving startup culture with the slower, safety-critical nature of energy systems. Electricity infrastructure cannot operate on a “move fast and break things” model. Success will depend on combining Silicon Valley’s speed and creativity with the reliability, durability, and public accountability that energy systems demand. If that balance is achieved, the future of renewable energy will be not just cleaner, but smarter and more resilient as well.